Key Highlights
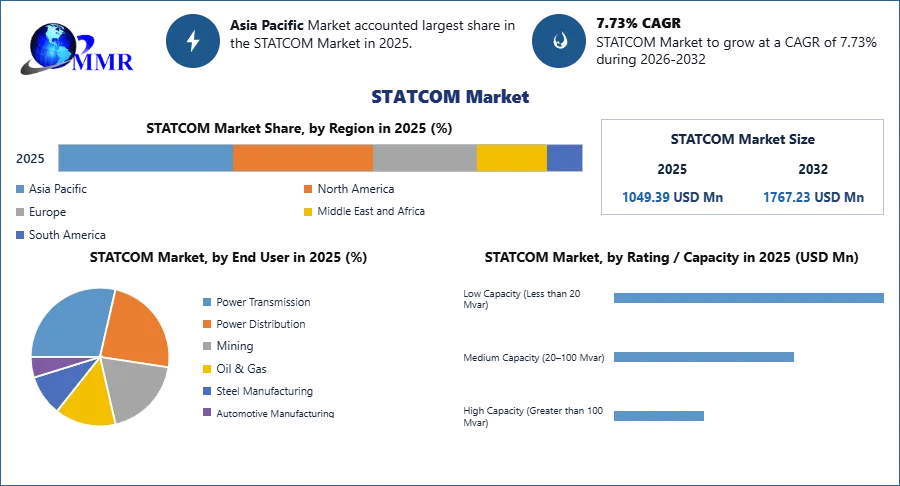
The global STATCOM market achieved an operational valuation of USD 1,049.39 million in 2025.
Total revenue is projected to reach USD 1,767.23 million by 2032, advancing at a calculated 7.73% CAGR.
The power transmission industry sector maintained absolute structural dominance over heavy industrial application verticals.
Global adoption is fundamentally driven by long-term renewable energy integration, mining operations, and rolling mill stabilizations.
High initial procurement and system installation costs remain the central macroeconomic head-winds restricting immediate market expansion.
Why This Matters Now
The rapid de-carbonization of global energy architectures has pushed traditional power grid topologies past their physical design limits. As utility networks shut down stable, rotating fossil-fuel plants and integrate highly variable solar and wind assets, networks are losing the mechanical inertia required to keep electrical frequencies stable. This structural mismatch creates immediate operational risks, exposing utility networks to sudden voltage drops, power quality issues, and widespread distribution blackouts.
For the high-power electronics and semiconductor manufacturing sectors, this transition creates a critical demand vector for advanced components. Modern STATCOM units are high-compute power systems that rely on dense arrays of Insulated-Gate Bipolar Transistors (IGBTs) and wide-bandgap semiconductor modules to adjust electrical characteristics in real time. Foundries and electronics manufacturing services (EMS) providers are scaling up production to supply high-reliability power semiconductors capable of handling rapid switching cycles under extreme electric stress.
Market Overview
STATCOM Market Empirical data compiled by Maximize Market Research demonstrates that the global STATCOM market concluded 2025 with an established value of USD 1,049.39 million. Driven by ongoing grid modernization programs and rising electricity consumption in developing economies, the sector is on track to compound at a 7.73% CAGR from 2026 to 2032. This continuous capital investment will elevate the total market scale to an estimated USD 1,767.23 million by the close of the 2032 forecast window.
STATCOM Market Revenue Expansion (2025 – 2032)

  2025: [■■■■■■■■■■■■■■■] USD 1,049.39 Mn
  2032: [■■■■■■■■■■■■■■■■■■■■■■■■■■] USD 1,767.23 Mn  (CAGR: 7.73%)
The underlying demand reflects the technical advantages of Static Synchronous Compensator platforms over legacy capacitors and rotary condensers. By using voltage-source converters to inject or absorb reactive current within milliseconds, these systems provide grid operators with faster response profiles, smaller physical installation footprints, and stable operations across fluctuating voltage ranges.
Key Trends Driving Growth
The operational and commercial scaling of the global STATCOM market is guided by four primary vectors:
Large-Scale Renewable Energy Integration
Wind and solar assets generate power through variable environmental inputs, creating sudden output fluctuations that disrupt local transmission links. Utility operators are placing large-scale STATCOM systems at renewable generation hubs to regulate voltages at the point of common coupling, ensuring compliance with strict regional grid codes.
Heavy Industrial and Mining Optimization
Industrial complexes utilize high-power equipment like rolling mills and electric arc furnaces that draw large, irregular currents, inducing severe voltage flicker on local distribution lines. Deploying dedicated STATCOM arrays stabilizes these local industrial lines, protecting sensitive automation machinery and avoiding penalty fees from municipal utilities.
Rising Urbanization in Developing Economies
Rapid population movements into urban centers across developing nations are straining existing distribution pipelines. Municipalities are installing compact, automated voltage compensation hardware to increase the transmission capacity of existing underground lines, delaying the need for expensive new right-of-way infrastructure investments.
Integration with Advanced Energy Storage Systems
System designers are increasingly pairing active STATCOM power circuits with local battery storage units. This hybrid combination allows the system to provide simultaneous reactive compensation and active power injection, giving grid operators a versatile tool to manage both short-term voltage blips and longer-term frequency imbalances.
𝐃𝐨𝐰𝐧𝐥𝐨𝐚𝐝 𝐏𝐃𝐅 𝐁𝐫𝐨𝐜𝐡𝐮𝐫𝐞 @ https://www.maximizemarketresearch.com/request-sample/70411/
Segment Insights
Power Transmission Industry (Dominant Segment): Maintained absolute market dominance, driven by utility-level investments to upgrade cross-border transmission networks with fast-response voltage control links.
Heavy Industry: Captures large capital allocations as metal processors and chemical plants deploy automated compensation units to stabilize dedicated electric arc furnaces.
Renewable Energy Generation: Represents the fastest-growing application vertical, expanding rapidly as wind and solar developers build out high-voltage substation connections to comply with grid rules.
Regional Growth Story
Geographical deployment patterns show heavy capital commitment across major semiconductor, electronics manufacturing, and infrastructure hubs. Developing economies are leading the physical installation volumes, using urbanization and expanding industrial sectors to modernize their national infrastructure networks. These nations are prioritizing high-voltage STATCOM installations to link distant renewable generation projects with high-demand manufacturing zones.
Concurrently, established manufacturing centers like the United States, Taiwan, South Korea, Japan, and Germany are driving technical innovation in the components that power these systems. These regions are leveraging their advanced foundry ecosystems to design next-generation power semiconductor architectures, focusing on improving the thermal efficiency and voltage limits of IGBT modules to lower the overall lifecycle costs of utility-scale hardware.
Competitive Landscape
The competitive strategies seen among top participants show a clear shift away from selling simple electrical components toward delivering fully automated power quality platforms:
Siemens Energy and ABB Ltd lead the utility transmission market by engineering large-scale, custom STATCOM installations that combine high-voltage power electronics with real-time software diagnostics, protecting their positions in major grid modernization projects.
General Electric and Mitsubishi Electric Corporation are focusing their engineering pipelines on high-reliability systems for heavy industrial clients, ensuring their hardware can withstand the severe thermal and electrical environments found near steel mills and heavy mining operations.
Schneider Electric and Eaton Corporation are targeting the decentralized infrastructure space, building modular, mid-voltage STATCOM products tailored for rapid installation across expanding data centers and medium industrial processing sites.
Recent Developments
System engineers successfully integrated real-time digital simulator testing frameworks into production lines, allowing foundries to validate power chip performance under simulated grid fault conditions before final assembly.
Equipment manufacturers expanded the use of modular multilevel converter (MMC) topologies within utility-grade systems, lowering harmonic distortion and reducing the need for large, expensive external filter fields.
Industrial facilities integrated automated edge-monitoring interfaces into localized control hubs, allowing technicians to track STATCOM thermal profiles and switching frequencies remotely.
Component suppliers ramped up production of high-current power semiconductor press-pack modules, improving system reliability by ensuring safe failure paths during extreme transmission grid short-circuits.
Strategic Implications
The changing structural needs of the global energy grid carry direct strategic priorities for power electronics OEMs, foundries, and industrial infrastructure investors.
The Grid Balancing Transition
┌──────────────────────────────┐
│  Legacy Rotating Inertia     │ -> Mechanical stability from fossil plants (Declining capacity)
└──────────────┬───────────────┘
               ▼
┌──────────────────────────────┐
│  Automated Power Electronics │ -> Millisecond semiconductor switching via STATCOM networks
└──────────────────────────────┘
What changed? Grid stabilization has shifted from a slow, mechanical process handled by heavy steam turbines to a high-speed electrical process managed by power semiconductor switches. Why now? The accelerating retirement of traditional coal and gas facilities, combined with the rapid addition of variable renewable energy sources, means grid networks can no longer maintain voltage stability without fast-acting electronic intervention.
Who benefits? Semiconductor foundries that can deliver highly efficient, high-voltage IGBT modules will see long-term demand growth as utilities make STATCOM units standard infrastructure. However, project developers face a clear hurdle: implementation is currently limited by high initial procurement and installation costs. To overcome this obstacle and maintain project velocity, system manufacturers must focus on standardization and modular designs to lower upfront capital barriers for budget-conscious utilities.
Future Outlook
The next stage of the global STATCOM market will be defined by the widespread adoption of high-efficiency silicon carbide (SiC) power electronics within voltage-source converters. As foundries increase their manufacturing capacity for large-area wide-bandgap wafers, the switching losses of high-voltage controllers will fall significantly, allowing for more compact installations and lower ongoing cooling costs.
The dividing line between future market leaders and lagging firms will depend on their ability to integrate smart control software with advanced power hardware. Component providers and OEMs that deliver modular, software-managed STATCOM platforms capable of adapting to changing grid conditions will lead the utility sector, while suppliers stuck providing rigid, legacy hardware designs will be pushed out by more flexible digital power solutions.
Analyst Perspective
“The STATCOM market has entered a critical expansion phase as global grid operators confront the realities of a highly variable, renewable-dominated power supply. Traditional mechanical compensation is no longer fast enough to handle the rapid voltage fluctuations seen on modern transmission lines. Firms that focus on optimizing the manufacturing yield of high-power semiconductor modules while lowering initial installation costs through modular system designs will lead this USD 1,767.23 million market.”
— Alpana Patil, Research Analyst, Maximize Market Research
About Maximize Market Research
Maximize Market Research Pvt. Ltd. (MMR) is a global market research and consulting company that provides reliable, data-focused, and practical business insights. The firm serves a wide range of industries, including healthcare, pharmaceuticals, technology, automotive, electronics, chemicals, personal care, and consumer goods. Through market forecasts, competitive analysis, strategic consulting, and industry impact assessments, MMR helps organizations understand changing market conditions, identify growth opportunities, and make informed business decisions for long-term success.
2nd Floor, Navale IT Park Phase 3
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India
+91 9607365656
sales@maximizemarketresearch.com
