Key Highlights
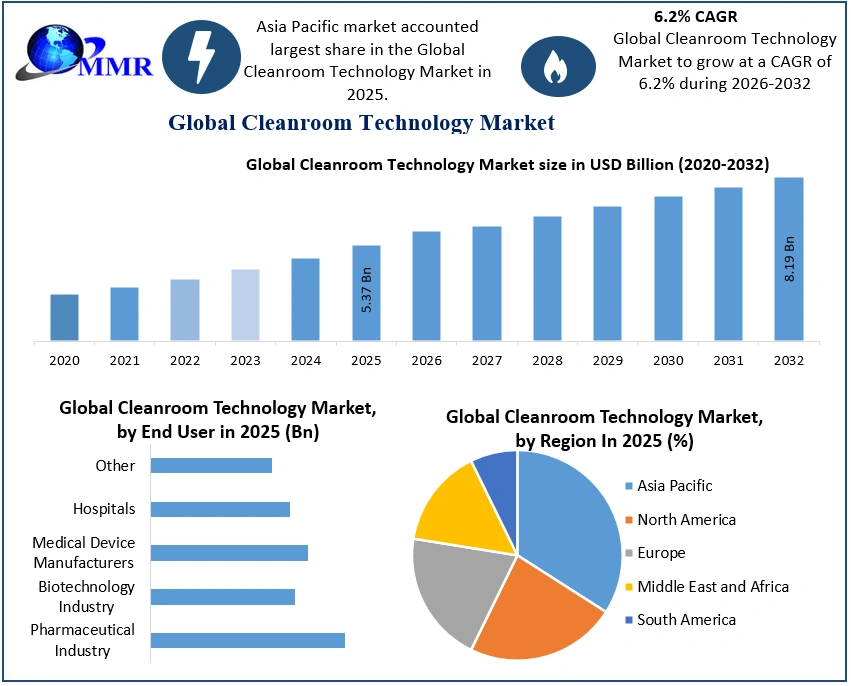
- Market size: USD 5.37 Billion (2025)
- Forecast value: USD 8.19 Billion (2032)
- CAGR: 6.2% (2025–2032)
- Rising demand from semiconductor and telecom hardware manufacturing ecosystems
- Expansion of high-purity environments for advanced electronics and data infrastructure
- Increasing alignment with AI-driven chip design and high-performance computing supply chains
Why This Matters Now
AI compute demand is redrawing the boundaries of semiconductor manufacturing. Every advanced chip, telecom component, and precision sensor now depends on ultra-clean production environments that reduce microscopic defects. Cleanroom infrastructure has shifted from a supporting utility to a strategic bottleneck in global digital expansion.
As governments and hyperscalers accelerate investments in chip fabrication and data center infrastructure, cleanroom systems are becoming mission-critical assets for supply chain resilience and technology sovereignty.
Market Overview
The Cleanroom Technology Market is transitioning from a niche industrial requirement into a foundational layer of global digital infrastructure. Valued at USD 5.37 Billion in 2025, the market is projected to reach USD 8.19 Billion by 2032, reflecting steady expansion at a CAGR of 6.2%.
Each incremental expansion in semiconductor fabrication, telecom equipment production, and advanced electronics manufacturing directly increases dependency on contamination-controlled environments. The implication is structural: cleanrooms are now embedded within the lifecycle of AI chips, 5G components, and high-density computing systems.
The market is no longer defined solely by pharmaceutical or laboratory use cases. Instead, it is increasingly shaped by digital infrastructure supply chains where even minor particulate contamination can disrupt billion-dollar chip yields or delay telecom network deployments.
Key Trends Driving Growth
AI computing expansion is the most powerful structural driver. As AI models scale, semiconductor complexity increases, requiring more advanced fabrication nodes that demand stricter environmental controls. Cleanrooms are evolving in parallel with chip architecture, particularly for high-performance GPUs, ASICs, and telecom processors.
Telecom modernization is another key force. The rollout of 5G and early-stage 6G research is intensifying demand for precision-manufactured RF components, base station hardware, and optical networking systems. These components rely on contamination-free production environments to ensure signal integrity and performance reliability.
Data center expansion is also reinforcing demand. Hyperscalers and cloud providers depend on a continuous supply of high-efficiency processors, memory modules, and networking hardware, all of which originate in cleanroom-controlled manufacturing environments. The implication is a direct link between cloud growth and cleanroom infrastructure scaling.
Cybersecurity and digital sovereignty concerns are indirectly influencing the market. Governments prioritizing domestic semiconductor production are investing in localized fabrication facilities, increasing demand for advanced cleanroom installations.
Get a free sample:https://www.maximizemarketresearch.com/request-sample/28733/
Segment Insights
- Dominant Segment: Not disclosed in the provided MMR report extract
- Fastest-Growing Segment: Not disclosed in the provided MMR report extract
While segmentation details are not specified in the supplied source, demand concentration is clearly shifting toward high-grade cleanrooms used in semiconductor and advanced electronics manufacturing. These environments represent the most capital-intensive and technically stringent applications, where air purity, particle control, and environmental monitoring directly impact production yields.
The implication is a market increasingly weighted toward ultra-high specification systems rather than conventional industrial cleanroom deployments.
Regional Growth Story
Asia Pacific continues to anchor global cleanroom deployment due to its dominant semiconductor manufacturing base. Countries such as China, South Korea, Japan, and Taiwan remain central to advanced chip production and electronics assembly ecosystems. This concentration intensifies demand for next-generation cleanroom facilities integrated into high-volume fabrication plants.
North America is witnessing accelerated investment driven by semiconductor reshoring initiatives and AI infrastructure expansion. The United States is prioritizing domestic chip manufacturing capacity, which is translating into large-scale cleanroom construction for advanced fabrication nodes.
Europe, particularly Germany, is strengthening its position through precision engineering and automotive electronics manufacturing. Cleanrooms are increasingly integrated into EV semiconductor supply chains and industrial automation systems.
India is emerging as a strategic manufacturing alternative, supported by policy-driven semiconductor and electronics production initiatives. This is expected to gradually expand cleanroom infrastructure requirements across new industrial corridors.
Competitive Landscape
The competitive environment is defined less by product differentiation and more by capability depth in engineering, contamination control precision, and integration with advanced manufacturing ecosystems.
Cleanroom solution providers are moving toward end-to-end facility design models, combining HVAC systems, modular cleanroom architecture, monitoring sensors, and automation platforms. This shift signals a broader transition toward integrated infrastructure ecosystems rather than standalone installations.
Market leadership is increasingly tied to the ability to support semiconductor fabs and telecom hardware manufacturers operating at sub-micron and nanometer scales. Companies that can align cleanroom performance with AI chip fabrication requirements gain structural advantage in long-term contracts.
Strategically, the market is consolidating around firms capable of delivering scalable, energy-efficient, and digitally monitored cleanroom environments. This aligns with broader enterprise trends in automation, predictive maintenance, and smart facility management.
Recent Developments
- Expansion of semiconductor fabrication capacity driving demand for advanced cleanroom installations
- Increased investment in AI chip manufacturing ecosystems requiring ultra-low particulate environments
- Telecom infrastructure modernization accelerating demand for precision manufacturing facilities
- Growing integration of digital monitoring systems in cleanroom operations for real-time contamination control
- Rising adoption of energy-efficient HVAC and filtration systems to support sustainability goals
Strategic Implications
Cleanroom Technology is becoming a hidden enabler of digital transformation. Without contamination-controlled manufacturing environments, AI chips, telecom components, and cloud infrastructure hardware cannot scale reliably.
For semiconductor manufacturers, cleanroom efficiency directly determines yield economics. For telecom operators and equipment suppliers, it defines network deployment timelines. For cloud providers, it shapes supply chain stability for compute hardware.
The strategic shift is clear: control over cleanroom-enabled manufacturing capacity increasingly translates into control over digital infrastructure leadership.
Future Outlook
The Cleanroom Technology Market will increasingly align with the trajectory of AI-driven computing, telecom network densification, and semiconductor sovereignty strategies. Demand will concentrate in ultra-high purity environments supporting next-generation chip architectures and advanced electronics manufacturing.
As AI, 5G evolution, and cloud infrastructure scale globally, cleanroom capability will separate digital leaders capable of secure, high-yield manufacturing from laggards constrained by supply chain fragility.
Analyst Perspective
“Cleanroom technology is no longer a back-end industrial requirement. It is becoming a strategic constraint in semiconductor and telecom manufacturing ecosystems where precision determines digital competitiveness,” says Yash Ghosalkar, Analyst at Maximize Market Research.
About Maximize Market Research
Maximize Market Research Pvt. Ltd. (MMR) is a global market research and consulting company that provides reliable, data-focused, and practical business insights. The firm serves a wide range of industries, including healthcare, pharmaceuticals, technology, automotive, electronics, chemicals, personal care, and consumer goods. Through market forecasts, competitive analysis, strategic consulting, and industry impact assessments, MMR helps organizations understand changing market conditions, identify growth opportunities, and make informed business decisions for long-term success.
2nd Floor, Navale IT Park Phase 3
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India
+91 9607365656
sales@maximizemarketresearch.com
