Key Highlights
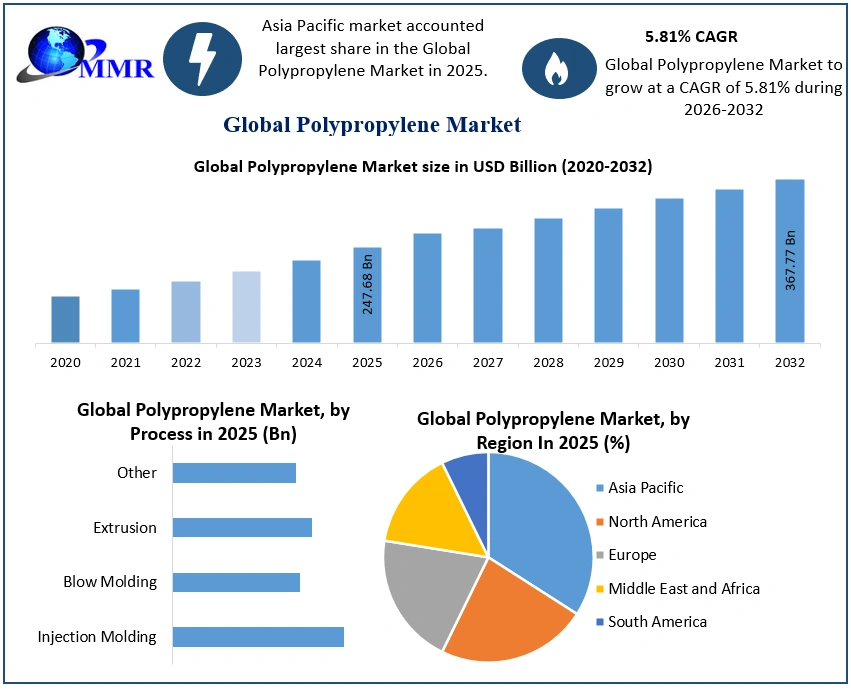
The global polypropylene market achieved a valuation of USD 247.68 billion in 2025 and is projected to expand to USD 367.77 billion by 2032.
Market revenue is advancing at a compounded annual growth rate (CAGR) of 5.81% over the 2026 to 2032 forecast period.
The homopolymer segment dominated the product type landscape in 2025 due to its pure structural composition and high mechanical strength.
Injection molding emerged as the dominant processing technology in 2025, driven heavily by large-scale components in the automotive and packaging industries.
China is poised to inject approximately 17 MMT of new polyethylene and polypropylene capacity over the next five years, altering regional cost dynamics.
Why This Matters Now Volatile feedstock pricing and unprecedented capacity waves are rewriting the economics of polyolefins production. For industrial procurement leaders and chemical manufacturers, the market presents a dual challenge of navigating near-term raw material price volatility while adapting to an oversupplied horizon driven by aggressive infrastructure builds in East Asia.
Compounding these supply dynamics is a synchronized regulatory and societal push toward circular economy adoption. As governments mandate higher recyclability standards, producers are forced to balance the cost-efficiency of conventional fossil-derived monofilaments against the capital-intensive commercialization of sustainable alternatives, making asset modernization an immediate survival imperative rather than a long-term strategy.
Market Overview The global polypropylene market Size closed 2025 with an established valuation of USD 247.68 billion. Operating under a steady 5.81% CAGR from 2026 to 2032, the sector is on track to reach USD 367.77 billion by the end of the forecast period. As a highly versatile thermoplastic polymer within the polyolefin group, polypropylene’s physical properties are derived directly from the polymerization of propylene monomers, sourced from traditional petroleum or natural gas streams.
This industry remains deeply sensitive to raw material feedstock pricing, which fluctuates alongside upstream crude oil cycles and geopolitical disruptions. Competition among global and regional manufacturers operates at one of the highest levels across all polymeric material sectors. This intensity is compressing margins, forcing top-tier market participants to aggressively invest in manufacturing asset modernization and targeted research and development to sustain cost competitiveness.
Key Trends Driving Growth Downstream application diversity across packaging, textiles, consumer goods, and medical devices serves as the primary engine for sustained volume consumption. The packaging industry commands significant volume due to the global expansion of e-commerce channels, food preservation needs, and consumer goods shipping requirements. Polypropylene’s lightweight profile, moisture resistance, and physical durability make it an indispensable choice for flexible films and rigid containers alike.
Simultaneously, the automotive sector relies on the material to meet vehicle weight reduction mandates. Polypropylene is utilized to manufacture bumpers, interior trims, dashboards, and complex injection-molded assemblies. Furthermore, accelerating urbanization and infrastructure development in emerging economies support volume placement in the construction sector, where the polymer is processed into structural pipes, durable sheets, and insulation materials.
Segment Insights
Dominant Type: Homopolymer Segment. Composed exclusively of repeating propylene monomers, this highly pure formulation dominated the global market share in 2025. Its highly crystalline structure provides optimal mechanical stiffness, high tensile strength, and superior heat resistance, making it the preferred choice for demanding industrial and structural applications.
Dominant Process: Injection Molding Segment. Holding the largest market share in 2025, injection molding is the leading manufacturing process for large-scale production. The process offers extreme cost-efficiency when melting and shaping polypropylene resin into complex automotive components and durable consumer goods, securing its dominant position through the 2032 horizon.
Fastest-Growing Segment: Not available. (Note: The source report details segmented structural dominance for Homopolymer and Injection Molding but does not disclose a separate fastest-growing statistical segment designation).
Regional Growth Story The Asia-Pacific region commands the global polypropylene landscape, powered by rapid industrialization, expanding urban centers, and a rising middle class across China and India. This regional dominance is reinforced by extensive local manufacturing assets that not only satisfy domestic industrial consumption but also feed international export pipelines.
China, in particular, is exerting profound structural influence as a low-cost polyolefins provider, partially accelerated by coal-to-olefins (CTO) technology installations. Over the next five years, China is projected to add roughly 17 MMT of new polyethylene and polypropylene capacity. This massive volume influx is intentionally designed by regional authorities to exceed local baseline demand, aiming to subsidize and drive employment within downstream manufacturing facilities while introducing substantial pricing volatility into global trade flows.
Competitive Landscape The global market structure is characterized by intense fragmentation and high-stakes capacity additions that shift regional pricing power. Major multi-national chemical syndicates are adjusting their footprints to embed production closer to high-growth consumer hubs. This strategic positioning allows top-tier players to mitigate supply chain disruptions, optimize logistics costs, and directly serve localized automotive and packaging clusters.
Capital allocation trends indicate that market leaders are moving away from purely speculative capacity to highly integrated mega-sites. By co-locating olefin cracking with downstream polymerization units, manufacturers achieve maximum thermal and material integration. This structural shift effectively lowers the cash-cost curve of production, giving integrated players a clear competitive edge over non-integrated, merchant-monomer-dependent producers during periods of low petrochemical margins.
Recent Developments
On January 08, 2026, BASF SE disclosed advanced construction milestones at its integrated Verbund site in Zhanjiang, China, integrating dedicated downstream polypropylene units to anchor its olefins production base and directly supply the Asia-Pacific automotive and packaging markets.
On September 15, 2025, Formosa Plastics Corporation USA commissioned the largest horizontal polypropylene reactor in North America at its Point Comfort, Texas facility, injecting 550 million pounds of capacity to alter domestic supply balances.
Strategic Implications The massive infrastructure additions by market leaders signal a structural transition toward localized production hubs. BASF’s Zhanjiang expansion underscores a deliberate corporate strategy to secure low-cost asset integration within the world’s largest automotive cluster, bypassing traditional import risks. Concurrently, Formosa’s mega-reactor installation in Texas increases North American capacity, intensifying domestic competition and pressuring margins for high-cost producers lacking direct feedstock integration.
For procurement executives, these investments mean that sourcing patterns must pivot toward localized, asset-integrated suppliers to shield operations from volatile freight rates. For standalone polymer compounders, the expansion of these massive integrated sites presents a clear margin threat, as primary resin producers capture greater pricing power through superior upstream integration and optimized energy configurations.
Future Outlook Environmental constraints, raw material volatility, and alternative material competition will test industry resilience over the coming decade. The non-biodegradable nature of conventional polyolefins continues to invite strict regulatory penalties and public resistance, driving interest toward bio-based polymers and alternative substrates. While capital investments are flowing into advanced recycling technologies, regions with underdeveloped sorting and collection infrastructure face persistent compliance hurdles. Ultimately, long-term profitability will belong exclusively to integrated chemical producers that successfully modernize assets to run on flexible feedstock configurations while deploying scalable recycling solutions.
Analyst Perspective “The global polypropylene market is navigating a critical supply-side recalibration,” stated Ankita Kagawade, Research Analyst at Maximize Market Research. “As massive capacity injections outpace near-term demand, long-term market leadership will be defined by producers that successfully decouple from raw material volatility through asset modernization and advanced circular economy integration.”
