Key Highlights
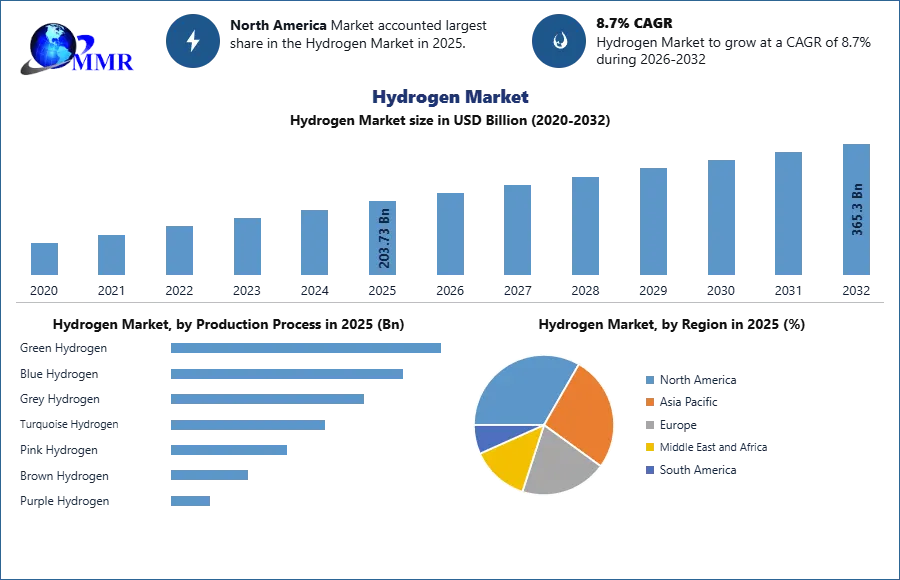
- Market valued at USD 203.73 billion in 2025.
- Expected to reach USD 365.30 billion by 2032.
- Forecast CAGR of 8.7% during 2026–2032.
- Green hydrogen emerges as the leading production pathway.
- Transportation remains the largest application segment.
- Electrolysis becomes the preferred production technology for low-carbon hydrogen.
- North America leads infrastructure development, while Asia Pacific records the fastest expansion.
- Government decarbonization strategies continue accelerating investment worldwide.
Why This Matters Now
Hydrogen has moved beyond pilot projects into large-scale industrial deployment. Governments, energy companies, and manufacturers are investing billions to reduce carbon emissions while strengthening long-term energy security. Falling renewable energy costs and improving electrolyzer technologies are making green hydrogen commercially viable across transportation, heavy industry, chemicals, and power generation, fundamentally reshaping global energy markets.
Market Overview
Hydrogen Market serves as a versatile energy carrier with applications across transportation, industrial manufacturing, electricity generation, refining, and chemical production. Unlike conventional fossil fuels, hydrogen produces only water during fuel cell operation, making it a critical component of global decarbonization strategies.
Market demand is expanding as governments introduce ambitious net-zero policies and industries seek practical alternatives to carbon-intensive fuels. Steel manufacturing, ammonia production, refining, and heavy transportation represent major consumption sectors where hydrogen offers substantial emissions reductions.
Supply remains dominated by fossil fuel-based production. However, renewable-powered electrolysis is rapidly gaining market share as investments increase in green hydrogen facilities and supporting infrastructure.
Macroeconomic drivers include climate legislation, renewable energy expansion, industrial electrification, international hydrogen trade initiatives, and rising capital investment in clean energy infrastructure.
Key Trends Driving Growth
Green Hydrogen Becomes the Strategic Investment Priority
Renewable-powered electrolysis is transforming hydrogen production by eliminating direct carbon emissions. Governments are supporting large-scale projects through subsidies, tax incentives, and national hydrogen strategies.
Electrolyzer Technology Advances Improve Economics
Technological improvements are increasing electrolyzer efficiency while reducing production costs. Standardized plant designs and manufacturing scale are lowering capital expenditure and accelerating commercial deployment.
Hydrogen Infrastructure Expands
Investment in hydrogen pipelines, storage facilities, refueling stations, and export terminals is improving supply chain connectivity and enabling wider commercial adoption.
Transportation Sector Accelerates Adoption
Fuel cell electric vehicles are gaining traction in heavy-duty transport, logistics, and public transit where battery-electric alternatives face operational limitations.
International Hydrogen Trade Emerges
Cross-border infrastructure development and international partnerships are creating new export opportunities for renewable hydrogen producers while strengthening global supply diversification.
Explore detailed analysis, insights, and growth opportunities
Segment Insights
Dominant Segment: Green Hydrogen
Green hydrogen leads the production process segment due to accelerating decarbonization initiatives and increasing renewable electricity availability. Electrolysis powered by wind and solar energy eliminates carbon emissions associated with conventional hydrogen production.
Supportive government policies and declining renewable energy costs continue improving commercial competitiveness.
Business impact: Producers investing in green hydrogen facilities gain long-term regulatory advantages and access to premium low-carbon industrial markets.
Fastest-Growing Segment: Transportation
Transportation represents the fastest-growing application as hydrogen fuel cell vehicles gain adoption across commercial fleets, heavy-duty trucking, buses, and logistics operations.
Expanding hydrogen refueling infrastructure and government incentives continue reducing commercialization barriers.
Business impact: Vehicle manufacturers, infrastructure developers, and hydrogen suppliers benefit from expanding demand for zero-emission mobility solutions.
Additional Key Sub-Segments
Merchant Hydrogen
Merchant hydrogen dominates the market by supplying multiple industrial customers across transportation, chemicals, refining, and manufacturing.
Its centralized production model enables suppliers to expand capacity while serving diverse end-user industries.
Electrolysis Technology
Electrolysis is becoming the preferred production technology due to its compatibility with renewable electricity and carbon-free hydrogen generation.
Growing investments in large-scale PEM electrolyzers are improving production efficiency while reducing operating costs.
Industrial Applications
Industrial hydrogen demand remains strong across ammonia production, methanol manufacturing, refining, and steel production, where hydrogen replaces carbon-intensive feedstocks and processes.
Regional Growth Story
North America
North America maintains leadership through advanced hydrogen infrastructure, substantial public funding, and large-scale clean energy programs. Government initiatives continue accelerating commercial deployment while encouraging private-sector investment.
Asia Pacific
Asia Pacific represents the fastest-growing regional market. Japan, South Korea, China, and India are expanding hydrogen production capacity through national hydrogen roadmaps, industrial investments, and renewable energy integration. Strong manufacturing capabilities position the region as a future global production hub.
Europe
Europe continues building an integrated hydrogen economy through cross-border infrastructure development, hydrogen corridors, and aggressive decarbonization targets. Regional cooperation supports market standardization and international hydrogen trade.
Middle East, Africa and South America
Saudi Arabia, Chile, and South Africa are leveraging abundant renewable resources to establish competitive green hydrogen export industries. These regions are increasingly attracting international investment aimed at serving global hydrogen demand.
Competitive Landscape
The hydrogen market is highly competitive, combining established industrial gas companies with renewable energy developers, fuel cell manufacturers, and technology innovators.
Air Liquide International S.A. and Linde plc continue strengthening leadership through integrated hydrogen production, distribution, and infrastructure investments. Their global industrial gas networks provide significant competitive advantages in scaling commercial hydrogen supply.
Technology specialists including Plug Power, Ballard Power Systems, Nel ASA, FuelCell Energy, and Green Hydrogen Systems are advancing fuel cell systems and electrolyzer technologies that improve production efficiency and commercial deployment.
Energy companies including Shell PLC, Chevron Corporation, ExxonMobil Corporation, Engie SA, Repsol, Reliance Industries Limited, Adani Green Energy, and Iberdrola SA are expanding hydrogen portfolios to diversify low-carbon energy businesses.
Strategic partnerships increasingly define market competition as companies combine infrastructure expertise, renewable generation, manufacturing capabilities, and technology development to accelerate commercialization.
Recent Developments
- March 2026: European Gas Transmission System Operators called for harmonized EU standards to accelerate cross-border hydrogen pipeline development.
- March 2026: Copenhagen Infrastructure Partners and Hy2gen cancelled a planned 240 MW renewable hydrogen and ammonia project in Norway, highlighting investment challenges.
- December 2025: Hystar partnered with McDermott to develop a standardized 100 MW PEM electrolyzer-based green hydrogen plant design.
- July 2025: Hy24 and Shanghai REFIRE signed an agreement to expand green hydrogen production and fuel cell mobility solutions.
- July 2025: Envision Energy commissioned a 500 MW electrolysis facility in China, establishing one of the world’s largest operational green hydrogen production sites.
Future Outlook
Organizations that secure low-cost renewable electricity, scale electrolysis capacity, and build integrated hydrogen infrastructure will define the next phase of competition in the global hydrogen economy.
About Maximize Market Research
Maximize Market Research Pvt. Ltd. (MMR) is a global market research and consulting company that provides reliable, data-focused, and practical business insights. The firm serves a wide range of industries, including healthcare, pharmaceuticals, technology, automotive, electronics, chemicals, personal care, and consumer goods. Through market forecasts, competitive analysis, strategic consulting, and industry impact assessments, MMR helps organizations understand changing market conditions, identify growth opportunities, and make informed business decisions for long-term success.
Contact Us :
2nd Floor, Navale IT Park Phase 3
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India
+91 9607365656
sales@maximizemarketresearch.com
