Key Highlights
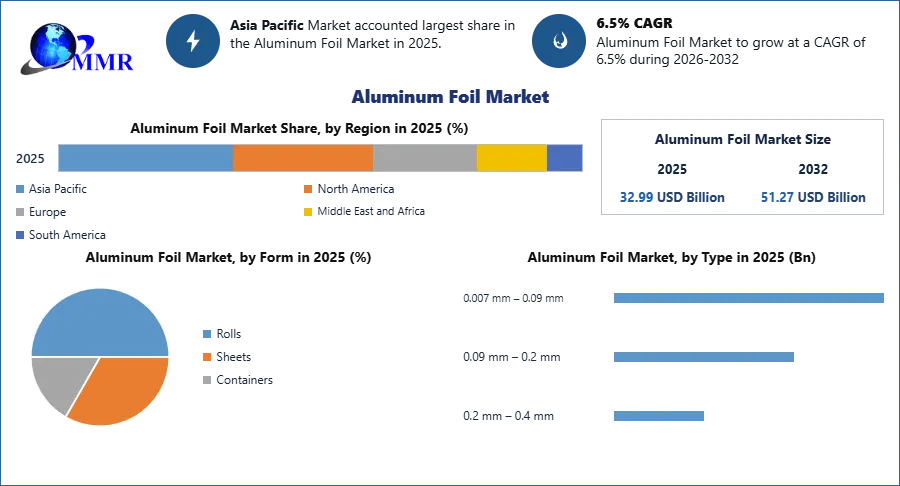
Market Scaling: The global aluminum foil market achieved a baseline valuation of USD 32.99 billion in 2025, moving toward a projected target of USD 51.27 billion by 2032.
Expansion Trajectory: Revenue and volume distribution are advancing at a steady 6.5% compound annual growth rate (CAGR) across the 2026 to 2032 outlook window.
Dominant End-User Segment: Packaging applications command the largest market share, serving as the essential barrier material protecting packaged food, ready-to-eat products, and online grocery deliveries.
Fastest-Growing Product Driver: Blister packaging and specialized lithium-ion battery sealing applications are growing rapidly, requiring tight foil gauge tolerances between 0.007 mm and 0.09 mm.
Geographic Leadership: The Asia-Pacific region controls a dominant 55% share of global revenue, supported by massive capacity additions and middle-class food consumption scaling in India and China.
Why This Matters Now
A profound regulatory and technical shift is hitting the flexible packaging and energy storage sectors, forcing corporate procurement leaders to quickly re-examine their barrier material choices. Traditional single-use plastic laminates face aggressive global phase-outs due to stringent recycling mandates and municipal safety crackdowns. Aluminum foil provides an immediate, infinitely recyclable substitute that stops the migration of moisture, oxygen, and light, allowing food processing plants and medical manufacturers to shield product integrity without risking non-compliance penalties.
The business pressure is intensifying due to the scaling of global electric vehicle (EV) battery gigafactories. Lithium-ion cell production lines demand high-purity aluminum foil for internal cathode current collectors and outer structural pouch cells. Procurement managers who fail to secure multi-year volume commitments from major aluminum rolling mills face immediate supply vulnerabilities, as surging battery cell manufacturing risks crowding out standard food and pharmaceutical foil capacities.
Market Overview
The global Aluminum Foil Market is entering a phase of rapid development linked to urban retail scaling and industrial energy storage infrastructure. Registering a market size of USD 32.99 billion in 2025, the sector is sustaining a 6.5% CAGR to reach USD 51.27 billion by 2032. This expansion reflects a major capital shift by packaging converters and industrial buyers toward high-barrier metal gauges over traditional plastic substrate alternatives.
Operationally, the market is categorized by foil thicknesses ranging from thin gauges (0.007 mm – 0.09 mm) up to thicker structural variants (0.2 mm – 0.4 mm), distributed as rolls, sheets, or pre-formed containers. The upstream supply structure depends heavily on primary aluminum ingot availability, energy pricing, and cold-rolling mill efficiency. Fluctuations in energy inputs directly affect smelting and rolling margins, driving manufacturing investments into automated thickness control and localized scrap recycling systems to stabilize pricing.
Key Trends Driving Growth
The most critical trend reshaping the product mix is the adoption of all-aluminum blister packaging, commonly known as Alu-Alu, within the pharmaceutical industry. Highly hygroscopic or light-sensitive medicine tablets and capsules cannot be safely packaged in standard barrier plastic sheets without risking early active ingredient degradation. Alu-Alu configurations utilize specialized thin-gauge foil layers to provide a perfect hermetic barrier, extending shelf lives for pharmaceutical companies operating in hot and humid tropical climates.
Concurrently, a massive surge in online grocery distribution and fast-food delivery networks is changing urban packaging consumption. Single-use foil containers and wrapper sheets are displacing plastic boxes due to their non-toxicity, superior heat retention, and total rigidity. These properties allow automated fulfillment centers to pack hot, ready-to-eat meals without risking container collapse or chemical leaching during transit, expanding baseline foil volumes in major cities.
Segment Insights
Packaging Segment (Dominant End-User): This application vertical holds the largest share of the aluminum foil market and is structured to maintain its dominance through 2032. Growth is sustained by high-volume demand for flexible pouches, laminated lids, and container foils across the food, beverage, personal care, and pet food sectors.
0.007 mm – 0.09 mm Gauges (Dominant Product Variant): Thin foil configurations represent the leading thickness segment, driven by their widespread lamination into multi-layer aseptic juice boxes, coffee pouches, and medical blister packs.
Lithium-Ion Sealing Material (Fastest-Growing Application): The utilization of high-purity aluminum foil as an internal sealing and current-conducting layer in EV batteries represents the fastest-accelerating growth vector, backed by state-level decarbonization mandates.
Regional Growth Story
The Asia-Pacific region operates as the central engine for the industry, holding a dominant 55% share of global revenue in 2025. This geographic concentration is anchored by massive capital investments from regional chemical and metallurgical companies. For instance, in India, SRF Limited approved a major capital allocation of INR 425 crore to establish a dedicated aluminum foil manufacturing plant in Jaitapur, Indore, aimed specifically at meeting rising domestic and international food packaging requirements.
North America is tracking a distinct development path, projected to expand at a 5.5% CAGR in revenue terms across the forecast period. This regional momentum is driven by the rapid construction of localized electric vehicle battery assembly plants in the United States. Furthermore, North American export-import balances are shifting following the reduction of trade tariffs on aluminum and steel by the United States government, optimizing international foil supply chains and expanding trade choices for procurement leaders.
Competitive Landscape
The global market structure is defined by a matrix of consolidated metal rollers and diversified packaging conglomerates. Top-tier operators protect their market position by maintaining direct ownership or long-term partnerships with primary bauxite smelters, insulating their rolling mills from raw ingot price spikes.
To counter low-cost commodity foil mills, market leaders are investing heavily in advanced surface functionalization. They are engineering specialized matte and bright finish foils with custom heat-seal lacquers and decorative printing substrates. These technical enhancements prevent foil tearing on automated high-speed packaging lines, allowing premium manufacturers to command higher processing margins and secure exclusive supply contracts with global consumer goods brands.
Recent Developments
High-Speed Rolling Upgrades: Leading metallurgical producers updated their cold-rolling plants with real-time laser gauge controllers, ensuring consistent foil thickness down to 0.006 mm for critical battery applications.
Aseptic Packaging Innovation: Major flexible packaging providers launched ultra-thin aluminum foil layers integrated with bio-based polymer substrates, reducing the total carbon footprint of dairy container lids.
Medical Blister Expansion: Specialized pharmaceutical packaging networks opened certified cleanroom foil slitting assets to fulfill rising demand for contaminant-free blister pack materials.
Strategic Implications
Strategic adjustments across the market indicate that top foil suppliers are moving away from supplying bulk rolling mill coils toward delivering specialized, slit-to-width pouch and container designs. This development raises technical entry barriers for new market players, as high-volume packaging lines require precise foil properties to operate without automated machine jamming. This trend shifts technical risk from the converter directly to the metal rolling mill.
Additionally, capital expenditure trends highlight a clear focus on securing localized supply lines. Germany remains one of the largest sources of non-subject aluminum foil imports into the United States, underscoring the interconnected nature of transatlantic metallurgical trade. For procurement leaders, maintaining diversified sourcing across European rolling mills and expanding domestic processing facilities is crucial to mitigate localized logistics blockades.
Future Outlook
The long-term development of the market will depend on how effectively rolling mills can integrate post-consumer aluminum scrap into high-purity foil production lines without introducing surface defects. Overcoming structural impurity limitations will allow aluminum foil to completely replace plastic barriers in heavy industrial insulation and technical building vapor barriers. Chemical and metallurgical enterprises that align their rolling investments with high-purity battery requirements and circular recycling networks will capture stable value as global packaging supply chains transition to sustainable materials.
Analyst Perspective
“Aluminum foil has shifted from a simple kitchen commodity into a highly critical structural barrier material for the energy transition and advanced pharmaceutical preservation. As industries move away from single-use plastics and scale up electric vehicle battery giga factories, the demand for precise, ultra-thin metal gauges is outpacing legacy rolling capacities. Organizations that secure long-term supply agreements with integrated, asset-heavy aluminum producers will protect their processing lines from future material allocation shortages. “Ankita Kagawade, Research Analyst, Chemicals & Materials
About Maximize Market Research
Maximize Market Research Pvt. Ltd. (MMR) is a global market research and consulting company that provides reliable, data-focused, and practical business insights. The firm serves a wide range of industries, including healthcare, pharmaceuticals, technology, automotive, electronics, chemicals, personal care, and consumer goods. Through market forecasts, competitive analysis, strategic consulting, and industry impact assessments, MMR helps organizations understand changing market conditions, identify growth opportunities, and make informed business decisions for long-term success.
2nd Floor, Navale IT Park Phase 3
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India
+91 9607365656
sales@maximizemarketresearch.com
