Key Highlights
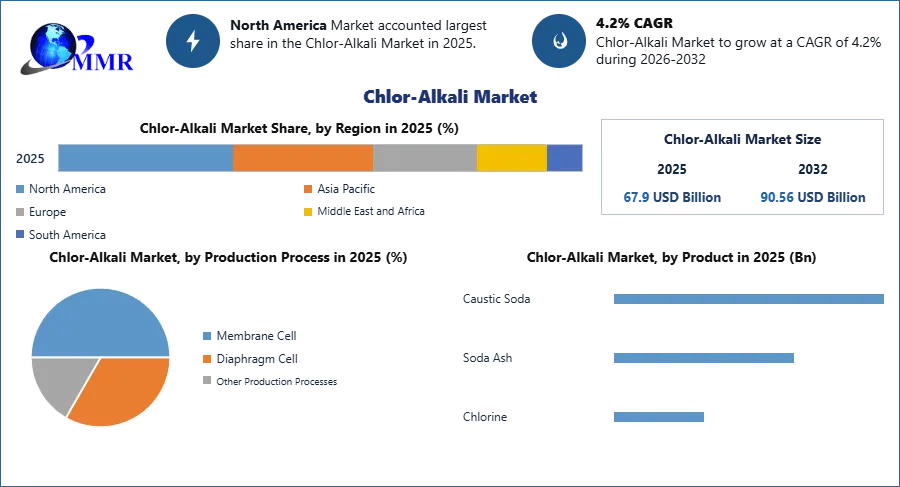
Market Valuation: USD 67.9 Billion in 2025, reaching USD 90.56 Billion by 2032.
Growth Trajectory: CAGR of 4.2% through the 2026–2032 period.
Regional Leadership: Asia Pacific controls over 50% of the market, with China alone accounting for over 60% of regional demand.
Dominant Product Segment: Caustic Soda.
Critical Operational Pivot: Strategic rationalization of high-cost, older electrolysis facilities in favor of modern, integrated value chains.
Why This Matters Now
The chlor-alkali sector is no longer defined merely by volume; it is defined by the efficiency of the electron. As energy prices fluctuate and carbon-intensive production processes face regulatory scrutiny, the industry is transitioning from a commodity-volume model to a precision-based, value-chain-integrated model. Capital allocators must distinguish between players merely adding capacity and those aggressively re-engineering their logistics and energy footprints.
Market Overview
The global Chlor-Alkali Market represents the foundational chemistry of the modern industrial economy, converting saltwater into essential building blocks like chlorine, caustic soda, and potassium hydroxide. In 2025, the market was valued at USD 67.9 billion. Growing at a steady CAGR of 4.2%, the revenue is forecast to climb to USD 90.56 billion by 2032. This growth is sustained by the omnipresence of chlorine derivatives in the petrochemical value chain—including PVC, propylene oxide, and polycarbonates—and the unwavering demand for caustic soda in soap, detergent, and pulp and paper manufacturing.
Key Trends Driving Growth
Downstream Vertical Integration: Manufacturers are increasingly tying production to end-user proximity, specifically in the construction and packaging sectors, to mitigate logistics costs and ensure supply chain reliability.
Environmental Remediation: The industry is aggressively phasing out legacy cell technologies that carry environmental liabilities, particularly those associated with mercury and carbon-intensive emissions.
Hydrogen Valorization: Leading producers are transforming the co-product hydrogen stream into a value-generating asset, utilizing it for clean energy or specialized chemical processing, thereby improving site-wide sustainability metrics.
Segment Insights
Dominant Segment (Caustic Soda): Caustic soda stands as the market leader due to its near-universal application across aluminum refining, soap/detergent production, water treatment, and textile processing. As the global paper and pulp industry evolves, the dependency on high-quality caustic soda remains a primary growth anchor.
Fastest-Growing Applications: The demand for chlorine derivatives, particularly in the production of PVC, epichlorohydrin, and methylene diphenyl diisocyanate (MDI), is outpacing general market growth, driven by surging infrastructure and construction activity in emerging economies.
Regional Growth Story
The Asia Pacific region is the global center of gravity for the chlor-alkali industry, commanding more than 50% of the total market share. Within this, China represents over 60% of regional demand. The expansion is bolstered by rapid urbanization and the proliferation of detergent and chemical manufacturing hubs in India, Thailand, Malaysia, and Vietnam. North America, while growing at a more mature 3.2% CAGR, remains a critical landscape for high-tech production and operational consolidation, with the U.S. and Canada leading the shift toward asset optimization.
Competitive Landscape
The competitive landscape is characterized by a “survival of the fittest” rationalization. Major incumbents are divesting non-core assets to shed debt and improve portfolio agility. The market is shifting away from fragmented, legacy-asset competition toward a structure dominated by players who control the integrated value chain—from feedstock to downstream derivatives. Pricing power is increasingly tied to the ability to supply regional markets with minimal logistics leakage rather than sheer production volume.
Recent Developments
Westlake Corporation (Feb 2026): Executed a strategic shutdown of three chlorovinyl facilities and one styrene unit in North America, targeting a $600 million improvement in EBITDA through asset footprint optimization.
Occidental Petroleum (Jan 2026): Finalized the $9.7 billion sale of its OxyChem subsidiary to Berkshire Hathaway, a move reflecting a broader trend of shifting chemical assets into stable, long-term investment portfolios.
Olin Corporation (Nov 2025): Entered a long-term EDC supply partnership with Braskem in Brazil, highlighting the increasing importance of regional strategic alliances to secure market share in high-growth territories.
Grasim Industries (Aug 2025): Commissioning major ECH and CPVC plants in India, cementing its position as a dominant integrated producer in the South Asian market.
Olin Corporation (Apr 2025): Commissioned a 15-ton-per-day hydrogen liquefaction plant in Louisiana, turning byproduct hydrogen into a sustainable financial asset.
Strategic Implications
The data signals a clear divergence in industry performance. Companies that continue to rely on legacy diaphragm or older technologies will face increasing cost pressure as energy prices and environmental compliance costs rise. Conversely, the “winners” are those investing in:
Asset Rationalization: Eliminating high-cost, high-emission production points.
Downstream Integration: Capturing the margin between raw chlorine/caustic and processed derivatives like PVC and MDI.
Circular By-product Management: Utilizing hydrogen and other streams to subsidize operational energy costs.
Future Outlook
The chlor-alkali sector is moving into a period of disciplined consolidation where operational excellence, rather than capacity expansion, will dictate long-term shareholder value. The market will reward producers who successfully integrate downstream applications and maintain the lowest cost-to-serve in the Asia Pacific and North American hubs, while those tethered to aging, high-emission assets will inevitably face acquisition or obsolescence.
Analyst Perspective
“The market is moving past the phase of indiscriminate expansion. We are observing a significant ‘flight to quality’ where manufacturers are prioritizing assets that offer integrated value chains and lower energy intensity. For the boardrooms of chemical majors, the focus has shifted entirely to supply chain resilience and the strategic monetization of co-products like hydrogen.” — Ankita Kagawade, Analyst, Maximize Market Research
About Maximize Market Research
Maximize Market Research Pvt. Ltd. (MMR) is a global market research and consulting company that provides reliable, data-focused, and practical business insights. The firm serves a wide range of industries, including healthcare, pharmaceuticals, technology, automotive, electronics, chemicals, personal care, and consumer goods. Through market forecasts, competitive analysis, strategic consulting, and industry impact assessments, MMR helps organizations understand changing market conditions, identify growth opportunities, and make informed business decisions for long-term success.
2nd Floor, Navale IT Park Phase 3
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India
+91 9607365656
sales@maximizemarketresearch.com
