Key Highlights
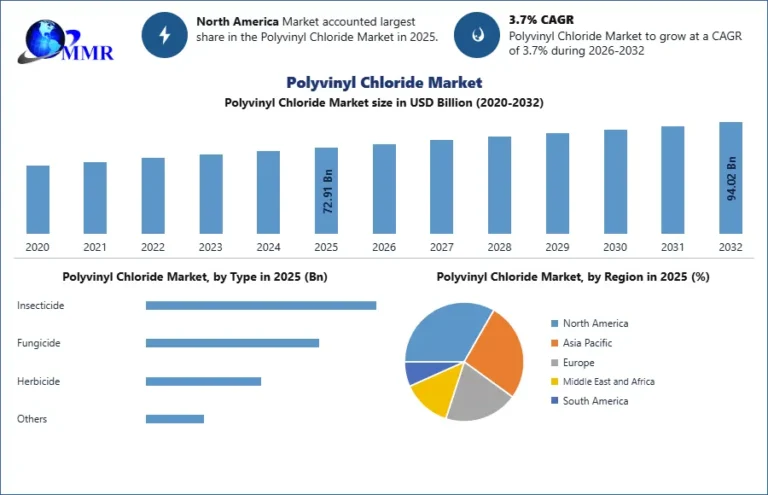
Global Market Scale and Valuation: Global Polyvinyl Chloride Market valued at USD 72.91 Billion in 2025.
Forward Projection: Projected to scale steadily to USD 94.02 Billion by 2032, advancing at a 3.7% CAGR.
Structural Cost Reconfiguration: Global market prices experienced a localized decrease in 2022, altering manufacturing margins and accelerating inventory absorption across global construction yards.
Segment Leadership: The building, construction, and infrastructure application domain held a dominant market share, running the absolute baseline of aggregate polymer demand.
Supply Chain Bottlenecks: Production configurations rely directly on the chlor-alkali process and fossil-derived ethylene feedstocks, leaving operations exposed to upstream petroleum volatility.
Key Regional Locomotive: The Asia-Pacific region dominated the global marketplace, driven by deep urban migration patterns and expanding manufacturing corridors across China.
Why This Matters Now
Global chemical processing groups and industrial construction procurement teams can no longer view vinyl polymers through the lens of simple legacy commodities. For boardroom executives, infrastructure planners, and large-scale manufacturing buyers, the polyvinyl chloride network represents a critical component under intense supply-chain and regulatory pressure. The rapid transition toward modernized water delivery networks and localized power grids requires immediate volume optimization. Production complexes that successfully balance volatile fossil-fuel feedstock prices with rising volume mandates will protect their structural margins. Meanwhile, legacy distribution networks that fail to implement efficient, low-energy processing methods risk facing rising operational costs and sudden raw material supply shocks.
Market Overview
The Global Polyvinyl Chloride Market is evolving from standard, low-cost architectural fittings into a highly specialized material segment split between high-volume civil infrastructure assets and sterile medical containment products. Achieving a baseline valuation of USD 72.91 Billion in 2025, the industry’s projected expansion to USD 94.02 Billion by 2032 underscores a global corporate reliance on durability, minimal maintenance, and cost-effective material substitution. As the third-largest thermoplastic polymer globally by total volume, the material is actively displacing wood, metal, and ceramic substrates in automated manufacturing setups due to its inherent resistance to water damage, structural decay, and harsh chemical exposure.
Advanced material engineering and integrated compounding configurations are fundamentally altering the basic overhead costs of the industry. Processing facilities are implementing advanced stabilization formulas and highly automated extrusion setups to maintain long operational runs without risking thermal degradation during high-temperature forming cycles. These continuous processing updates, combined with a significant industry shift toward large-scale modular production units, enable chemical compounding plants to maximize total volume yields. This operational evolution ensures full compliance with strict cross-border industrial validation terms and technical delivery standards.
Key Trends Driving Growth
The systematic displacement of traditional corroding metals and brittle concrete lines by heavy-duty PVC water supply and sewage piping networks serves as a powerful growth engine. Municipal engineering teams prioritize automated thermoplastic extrusion systems because they provide extended service lifespans and lower direct installation expenses across high-density urban infrastructure grids.
Rapid expansion within international medical manufacturing facilities drives significant volume demand for specialized, high-purity medical vinyl lines. Healthcare product engineering teams rely on flexible PVC compounds to manufacture flexible blood bags, sterile IV fluid pouches, oxygen masks, and specialized dialysis tubing lines where zero-contamination chemical integrity remains mandatory.
Escalating investment in regional telecommunications infrastructure and localized electrical grids creates a steady pipeline of specialized insulation and sheathing orders. The concentration of high-voltage sub-surface power cables and fiber-optic networks within modern industrial parks amplifies the continuous operational demand for low-voltage cable insulation and durable telecom duct assemblies.
Furthermore, shifting consumer preferences and rising ecological awareness force global operators to transition toward circular economy manufacturing configurations. This structural shift drives manufacturing organizations to invest heavily in modern mechanical recycling equipment and alternative, energy-efficient production processes to limit their overall carbon footprints and reduce historical dependencies on direct fossil fuel feedstocks.
Segment Insights
Dominant Segment: Building & Construction & Infrastructure Applications. Controlling the vast majority of global volume demand due to its critical integration into water distribution systems, sewage conduits, window profiles, and roofing sheets, this segment remains the central financial driver of the industry. Major buyers include public civil engineering authorities, commercial real estate developers, and automated structural component fabricators.
Critical Secondary Segments: Insulation & Sheathing and Medical Applications. These segments provide premium, high-margin revenue streams through the production of low-voltage automotive wiring assemblies, telecom cable coverings, and bio-compatible medical tubing.
Regional Growth Story
The Asia-Pacific region maintains absolute volume dominance in the global marketplace, driven by massive manufacturing expansions and extensive urban infrastructure modernization programs across China and India. Local development initiatives focused on extensive clean water distribution systems and the rapid expansion of localized automotive production hubs make the region the primary destination for top-tier global polymer brands.
North America holds a substantial share of advanced, high-value vinyl processing revenue, supported by a mature manufacturing base and a highly integrated network of petrochemical refineries. The United States market benefits from large-scale extraction operations, structured utility modernization programs, and strong corporate adoption patterns that prioritize durable, low-maintenance building materials like vinyl window profiles and siding.
In Europe, industry development is heavily shaped by strict regional sustainability mandates and changing chemical safety frameworks. European polymer manufacturers focus on optimizing closed-loop recycling loops and developing lead-free stabilizer formulations to satisfy regional environmental testing rules. Meanwhile, precision petrochemical manufacturing clusters in Japan and South Korea continue to pioneer advancements in high-clarity medical-grade polymers and specialized automotive underbody coatings.
Competitive Landscape
The global competitive profile features a highly consolidated mix of multinational chemical conglomerates and specialized polymer processing brands. Top-tier industry organizations rely on massive manufacturing scale, integrated upstream chlorine and ethylene supply chains, and extensive international logistics lines to secure multi-year volume contracts with global construction distributors.
To insulate their operational margins from volatile petroleum costs, leading producers focus on vertical asset integration and the optimization of large-scale manufacturing centers. Prominent global enterprises—including Formosa Plastics Corporation, Shin-Etsu Chemical Co., Ltd., Solvay, Lotte Chemical Corporation, and Vinnolit GmbH & Co. KG—maintain dominant international supply routes. These major players deploy licensed formulation systems to deliver application-specific vinyl resins directly to industrial extrusion lines worldwide.
Smaller regional compounding facilities and localized independent suppliers capture targeted market share by providing custom color matching, specialized additive blending, and flexible shipping timelines. By serving localized automotive and consumer packaging clusters, these mid-sized organizations remain critical supply chain partners for domestic manufacturing plants.
Recent Developments
Cross-Border Supply Infrastructure Optimization (2025–2026): Major international chemical corporations complete significant manufacturing upgrades at their primary production sites, optimizing vinyl monomer outputs to shield downstream processing lines from raw material shortages.
Advanced Medical-Grade Polymer Lines Expanded (Late 2025): Top-tier vinyl resin developers finalize massive refinery expansions to meet a sudden surge in high-purity medical tubing and sterile fluid bag orders from global healthcare providers.
High-Efficiency Carbon-Reduction Processing Deployed (Early 2026): Leading chemical technology suppliers introduce automated, low-energy separation modules designed to integrate directly into existing chlor-alkali lines, lowering power consumption during heavy manufacturing runs.
Regional Specialty Resin Acquisitions Concluded (2026): Prominent global polymer brands complete strategic asset buyouts of localized compounding specialist businesses, securing direct access to high-performance automotive interior trim supply lines.
Strategic Implications
For high-volume pipe extrusion plants, automated cable insulation facilities, and precision medical device manufacturers, maintaining a resilient and monitored polyvinyl chloride supply chain represents an absolute business priority. Production groups must establish long-term volume agreements and optimize inventory strategies to protect delicate manufacturing schedules from sudden upstream ethylene supply interruptions.
National industrial development authorities must view domestic chemical compounding facilities and regional polymer logistics networks as vital pillars of economic durability. Governments that establish clear, uniform quality testing frameworks and provide upfront structural incentives for energy-efficient production methods will successfully attract premium chemical manufacturing investments while protecting regional industrial stability.
Future Outlook
The next competitive era will belong to polyvinyl chloride operators who successfully combine absolute manufacturing scale with bio-attributed or highly recyclable polymer configurations. Corporate structures that direct their long-term development spending toward alternative renewable feedstocks, advanced mechanical separation lines, and energy-efficient chlor-alkali processing methods will lock in high-volume distribution contracts in tomorrow’s circular economy. Conversely, unhedged component suppliers that stick to unmonitored legacy fossil-fuel processing routes will face falling profit margins and shrinking access to modern sustainable building projects.
Analyst Perspective
“The global polyvinyl chloride market is entering an era defined by non-negotiable smart integration and predictive processing rules,” says Ankita Kagwade, Analyst at Maximize Market Research. “While traditional liquid and gas separation steps continue to secure huge, reliable baseline order volumes, future value expansion is shifting rapidly toward data-connected systems and verified sustainable filter designs. With the global market scaling toward USD 94.02 Billion by 2032, long-term commercial leadership belongs to producers who embed real-time condition sensors directly into their products. Moving beyond basic component replacements and moving toward automated, performance-driven resource management is now essential for defending processing margins in an increasingly regulated global manufacturing landscape.” – Ankita Kagwade
About Maximize Market Research
Maximize Market Research Pvt. Ltd. (MMR) is a global market research and consulting company that provides reliable, data-focused, and practical business insights. The firm serves a wide range of industries, including healthcare, pharmaceuticals, technology, automotive, electronics, chemicals, personal care, and consumer goods. Through market forecasts, competitive analysis, strategic consulting, and industry impact assessments, MMR helps organizations understand changing market conditions, identify growth opportunities, and make informed business decisions for long-term success.
2nd Floor, Navale IT Park Phase 3
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India
+91 9607365656
