Key Highlights
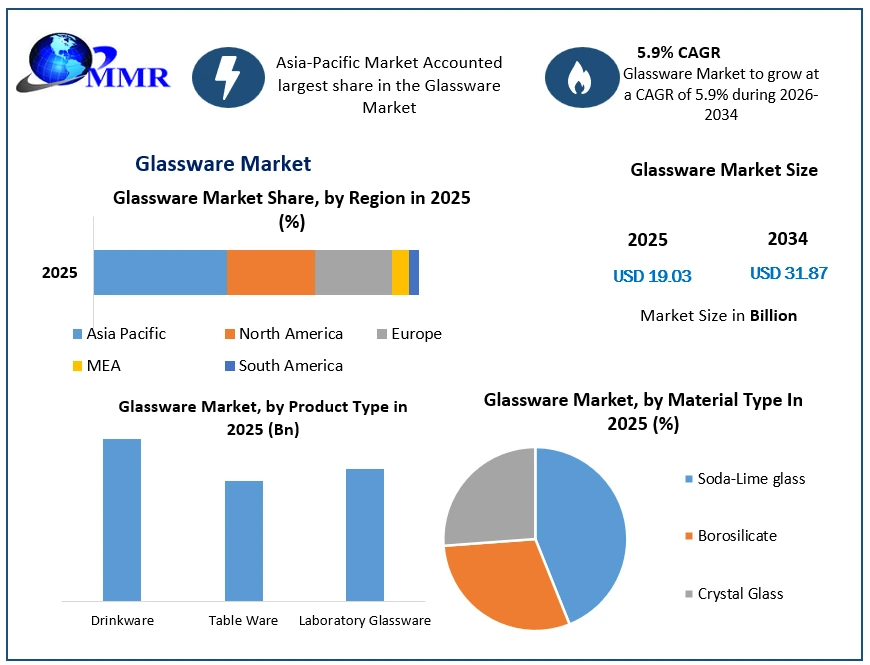
Glassware Market size was valued at USD 19.03 Billion in 2025 and is expected to reach nearly USD 31.87 Billion by 2034, growing at a CAGR of 5.9% from 2026 to 2034—strong, long-cycle growth for a mature material.
Growth is driven by demand for food and beverage packaging, household glassware and hospitality/tableware, all linked to how consumers buy, store and consume products.
Sustainability and recyclability of glass, premiumization in beverages and the rise of home entertaining and hospitality upgrades are key market drivers.
Europe currently holds a significant share of the global market, highlighting the role of regions with strong recycling systems and high adoption of glass packaging.
Why This Matters Now
A market heading from USD 19.03 Billion in 2025 to almost USD 31.87 Billion by 2034 at 5.9% CAGR means the world is buying more glass, not less, to hold what people eat and drink. For FMCG and food & beverage boards, that is not a materials footnote; it is a signal that packaging and serveware are becoming central to consumer trust, regulation compliance and brand value.
Every additional billion in glassware sales implies more products moving from plastic or mixed materials into glass bottles, jars and glasses. That shift touches capex, supply chains, marketing and ESG scores. Companies that treat glass as a strategic asset—rather than just a procurement line—will define what “premium, safe and sustainable” looks like on the shelf and at the table.
Market Overview
The global Glassware Market size is valued at around USD 19.03 Billion in 2025 and is forecast to reach nearly USD 31.87 Billion by 2034, expanding at a 5.9% CAGR. This trajectory reflects stable demand for glass in packaging, household use and hospitality, backed by regulatory and consumer pressure for recyclable materials.
Glassware spans containers (bottles, jars, vials), drinkware (tumblers, wine glasses, beer glasses), tableware (bowls, plates) and specialized items used across domestic kitchens, restaurants, bars and manufacturing. Food and beverage applications dominate value: soft drinks, juices, alcoholic beverages, sauces, spreads, dairy, and premium pantry items rely heavily on glass for visual appeal and perceived purity.
Market expansion is supported by both replacement of other materials and functional growth in categories using more premium packaging. Glass’s inertness and transparency make it attractive for brands seeking to showcase product quality and avoid chemical migration concerns, especially in health- and wellness-oriented segments.
Key Trends Driving Growth
Sustainability and circular economy pressure
Glass is infinitely recyclable without major loss of quality, and many markets have established collection and recycling systems. As regulators tighten rules on single-use plastics and extended producer responsibility, FMCG and beverage brands increasingly view glass as a safer long-term bet for meeting packaging obligations.
Premiumization in food and beverage
Consumers associate glass bottles and jars with premium quality and authenticity. Wine, beer, spirits, cold brew coffee, kombucha, juices, sauces and spreads often use glass to signal higher value. As premium segments grow, glass packaging demand rises, reinforcing its role as a key brand expression tool.
Health and clean-label perceptions
Glass is widely perceived as a safer, cleaner packaging option: inert, odourless, and free from concerns linked to certain plastics. For clean-label and natural-positioned foods and beverages, glass containers align with messaging around purity, minimal processing and ingredient transparency.
Home dining and entertaining
Post-pandemic shifts in home cooking and socializing have increased demand for household glassware—drinkware, serveware and storage jars. Consumers invest in better-looking, durable glass items that support both everyday use and entertaining, pushing category growth beyond institutional demand.
E-commerce and direct-to-consumer
Online food and beverage sales create new packaging logistics challenges but also highlight unboxing and presentation. Glass packaging must balance protection and aesthetics; brands that solve for both gain share. E-commerce offers visibility into packaging quality through reviews and social media, amplifying glassware’s impact on perception.
Request a Free Sample Copy or View Report Summary: https://www.maximizemarketresearch.com/request-sample/194202/
Segment Insights
Dominant Segment – Application: Food & Beverage Packaging Glassware
Glass bottles and jars for food and beverages form the dominant segment of the glassware market. This includes containers for soft drinks, alcoholic beverages, juices, sauces, spreads, dairy, and specialty foods. Packaging glass drives bulk volume and is tightly linked to brand and regulatory strategies.Dominance of packaging glass means supply security, design capabilities and recycling partnerships are non‑negotiable strategic issues for FMCG and beverage players.
Fastest-Growing Segment – Application: Hospitality and Premium Tableware
Hospitality and premium domestic tableware—wine glasses, cocktail glasses, elegant tumblers and decorated plates—are among the fastest-growing segments as hotels, bars and households upgrade experiences. Beach hotels, urban bars, cafés and restaurants adopt distinctive glassware to match brand identity.This segment’s growth signals that on‑premise settings are becoming more design‑sensitive; beverage and food brands must coordinate packaging with serveware aesthetics to create cohesive experiences.
Other Segments – Laboratory and Specialty Glassware
Specialty and laboratory glassware contribute niche but high-value demand, particularly in pharma and scientific applications. While less central for FMCG, these segments influence innovation in durability and precision that can trickle into consumer-grade designs.
Regional Growth Story
Europe
Europe holds a major share of the global glassware market, with around 35.6% of global market share in 2024. Strong recycling infrastructure, regulatory support for glass packaging and entrenched cultural preferences for glass bottles in beverages drive demand. For FMCG players, Europe often acts as a testing ground for advanced glass packaging and deposit schemes.
North America
In North America, growth is driven by craft beverages, premium food brands and rising sustainability commitments. Breweries, distilleries and specialty food producers use glass to differentiate, while retailers push private-label ranges in glass for higher perceived value.
Asia-Pacific and Emerging Markets
Asia-Pacific and other emerging regions see rising demand as middle classes grow and e-commerce expands. Local producers move upmarket with glass packaging to access global and urban consumers, while multinational brands adapt glass strategies to local infrastructure and cost realities.
Competitive Landscape
The Glassware Market features large container glass producers, tableware manufacturers and specialized designers. Container glass companies serve big beverage and FMCG contracts; tableware and drinkware brands target hospitality and consumer retail.
Competition revolves around design innovation, weight reduction, strength, energy efficiency in production and recycled content. Producers that can offer lighter yet durable bottles and jars help brands cut logistics costs and emissions without losing shelf presence.
In the next 12–24 months, expect deeper collaboration between glassmakers, FMCG brands and recyclers to secure cullet (recycled glass) supply and develop closed-loop systems. Companies that cannot guarantee reliable, sustainable capacity will face pressure as brands look to consolidate suppliers aligned with their ESG roadmaps.
Recent Developments
Expansion of lightweight glass bottle programmes to reduce transport emissions and material use.
Increased integration of recycled glass content in packaging, supported by investments in collection and processing infrastructure.
Growth in premium, design-led glassware lines for hospitality and home, including coloured, textured and branded pieces.
Development of glass packaging formats tailored to e-commerce demands—stronger designs, protective structures and compact sizes.
Strategic Implications for FMCG & Food & Beverage
Glassware decisions now sit at the intersection of brand, ESG and economics. For FMCG and food & beverage companies, container choice affects shelf impact, perceived quality, logistics cost and regulatory compliance. Poorly considered material shifts can increase cost or weaken brand cues; well-designed glass programmes can unlock premium pricing and sustainability credibility.
Ingredient and formulation teams should coordinate with packaging specialists to ensure product stability and sensory experience match glass’s advantages—aroma visibility, colour showcase, absence of flavour transfer. Marketing must communicate glass’s value clearly: purity, recyclability, heritage, or modern minimalism, depending on positioning.
On-premise strategies in hospitality and foodservice should align serveware with packaging. A premium drink in an ordinary glass misses potential value; conversely, distinctive glassware can elevate everyday products. Co‑branding opportunities between beverage makers and glassware designers can create signature experiences that travel across venues and social media.
Future Outlook
With the Glassware Market expected to grow from USD 19.03 Billion in 2025 to nearly USD 31.87 Billion by 2034 at 5.9% CAGR, glass will remain central to how food and beverages are packaged, served and experienced. Regulatory pressure and consumer preferences will likely strengthen glass’s role as a sustainable, premium material.
Innovation will focus on lighter, stronger designs, higher recycled content and better alignment with e-commerce and reuse models. Brands that treat glass partnerships as long-term strategic alliances—covering design, sustainability and supply security—will be positioned to lead.
In this environment, the winners will treat glassware as a core part of their value proposition and ESG strategy, while the losers will continue to buy containers on price alone—and discover that the vessels they chose quietly erode both margins and trust.
Related Reports
Global Flushing Systems Market https://www.maximizemarketresearch.com/market-report/global-flushing-systems-market/22309/
Global Water Free/Waterless Urinals Market https://www.maximizemarketresearch.com/market-report/global-water-free-waterless-urinals-market/44934/
Elliptical Market https://www.maximizemarketresearch.com/market-report/global-elliptical-market/86812/
Analyst Perspective
“Glassware has moved from being a silent container to a visible signal of quality and responsibility,” “With market size projected to rise from USD 19.03 Billion to nearly USD 31.87 Billion by 2034 at 5.9% CAGR, FMCG and food & beverage companies that lock in smart glass strategies—covering design, recyclability and supply resilience—will secure both premium shelf space and sustainability leadership.”-Siddhi Dole
About Maximize Market Research
Maximize Market Research Pvt. Ltd. (MMR) is a global market research and consulting company that provides reliable, data-focused, and practical business insights. The firm serves a wide range of industries, including healthcare, pharmaceuticals, technology, automotive, electronics, chemicals, personal care, and consumer goods. Through market forecasts, competitive analysis, strategic consulting, and industry impact assessments, MMR helps organizations understand changing market conditions, identify growth opportunities, and make informed business decisions for long-term success.
2nd Floor, Navale IT Park Phase 3
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India
+91 9607365656
sales@maximizemarketresearch.com
