Key Highlights
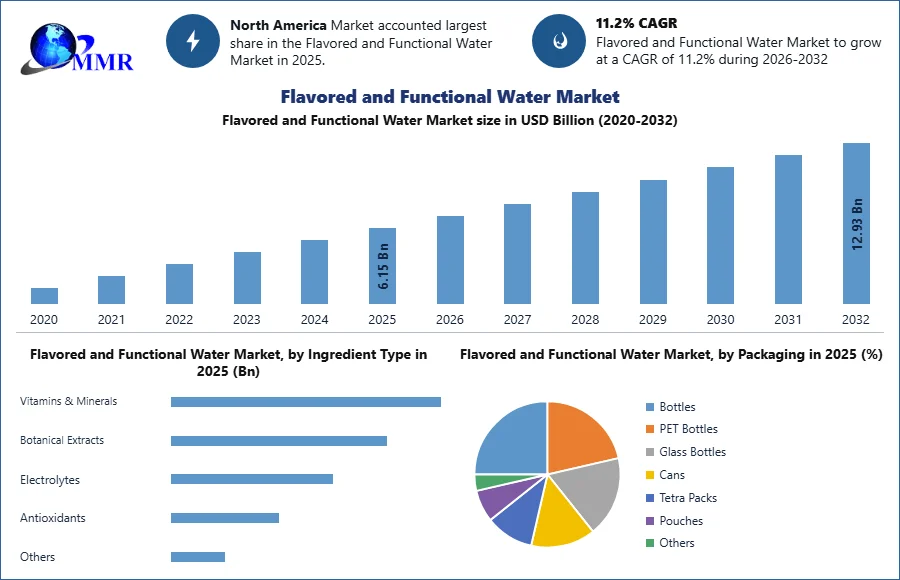
The global flavored and functional water market valuation will surge from USD 6.15 billion in 2025 to nearly USD 12.93 billion by 2032, exhibiting an 11.2% compound annual growth rate.
Flavored water commanded the dominant market position in 2025, leveraged by broad consumer appeal for weight management and sugar-free hydration.
Supermarkets and hypermarkets remain the primary volume engines for distribution, using localized shelf-space diversification to attract health-conscious household shoppers.
High manufacturing costs related to natural plant extracts and advanced fortification technologies act as severe margin barriers for mid-tier processors.
The functional beverage division is expanding rapidly due to consumer interest in targeted physiological benefits, including immunity protection and metabolic craving control.
Why This Matters Now
Beverage manufacturers face structural portfolio degradation if they continue to rely on legacy carbonated soda formulas to drive volume. Retail shelf-space is actively rotating away from traditional high-calorie sugary sodas as consumers migrate toward transparently clean, nutrient-dense alternatives. This structural shift means that brands missing a clear, fortified water strategy face immediate shelf de-listings and multi-market revenue contractions.
Furthermore, high baseline production costs present an immediate operational challenge for procurement teams seeking to scale these alternative beverages. Sourcing stable natural ingredients, plant extracts, and premium fortification compounds requires significant upfront capital that inflates final retail pricing. Packaging and formulation executives must immediately optimize their processing lines to absorb these cost pressures, or risk priced-out inventory in an increasingly competitive environment.
Market Overview
The Flavored and Functional Water Market operational matrix of the modern beverage industry is rapidly reorganizing around health-optimized liquid bases. Flavored and functional waters represent standard hydration solutions structurally augmented with vitamins, minerals, botanical extracts, and natural fruit fluids to deliver targeted physical benefits. These specialized formulations address consumer needs ranging from metabolic enhancement and blood system support to on-the-go stress reduction.
The baseline evaluation of this market reached USD 6.15 billion in 2025. Industrial intelligence establishes that total category revenue will climb to nearly USD 12.93 billion by 2032, propelled by a strong 11.2% compound annual growth rate. This rapid pace requires ingredient houses and packaging partners to systematically expand their raw material capacities to support global bottling networks.
Key Trends Driving Growth
Widespread lifestyle transformations act as the underlying economic driver for increased volume demands across global distribution nodes. Consumers are intentionally reducing their consumption of artificial sweeteners and chemical additives, favoring transparently clean hydration that fits easily into active daily routines. This market preference forces production lines to implement clean-label practices that deliver distinct sensory profiles without violating strict nutritional standards.
Concurrently, a wave of flavor experimentation is altering the product development priorities of international brand operators. Manufacturers are moving past basic fruit offerings to introduce complex, playful, and tropical blends designed to capture younger, adventurous demographics. This innovation cycle converts a commodity product like purified water into a premium sensory experience, allowing manufacturers to secure higher price points per volume unit.
𝐃𝐨𝐰𝐧𝐥𝐨𝐚𝐝 𝐏𝐃𝐅 𝐁𝐫𝐨𝐜𝐡𝐮𝐫𝐞 @ https://www.maximizemarketresearch.com/request-sample/79443/
Segment Insights
Flavored Water (Dominant Segment): This product type commanded the largest market share in 2025, driven by its reputation as a safe, refreshing alternative to standard carbonated soft drinks. The incorporation of natural plant extracts and real fruit juices provides established volume lines with steady consumer interest and consistent shipping frequencies.
Functional Water (Fastest-Growing Segment): Water varieties fortified with specific health-targeted components—such as vitamins, minerals, probiotics, and collagen—are showing high-velocity growth. Consumers view these products as active self-care tools that offer verifiable support for weight control and immunity enhancement.
Supermarkets & Hypermarkets: This distribution channel retains absolute volume dominance due to massive shelf presence and multi-pack promotional structures. Physical display diversification within large retail environments acts as a direct catalyst for impulse purchases by health-conscious shoppers.
Regional Growth Story
The geographical landscape of the water industry highlights a clear concentration of purchasing power inside North American borders, balanced by accelerating supply infrastructure across the Asia-Pacific territory. North America held the largest share of the flavored and functional water market in 2025, anchored by deep health awareness, advanced distribution systems, and strong household disposable income levels throughout the United States and Canada. This regional dominance forces established brands to constantly refresh their product portfolios to prevent consumer fatigue.
In parallel, production capacity is scaling up across the Asia-Pacific region, with Australia and China emerging as key manufacturing hubs. Growing urban middle-class populations in these areas are rapidly adopting westernized health habits, driving local investment in automated bottling and multi-tier fortification facilities. This localized production expansion allows regional operators to bypass long-distance shipping hurdles and directly counter imported international premium brands.
Competitive Landscape
Market participants are currently deploying significant capital to protect their core retail positioning and defend against independent disruptors. Leading brands are focused on continuous product extension strategies, adding advanced infusions like CBD, collagen, and active probiotics to capture high-margin, premium consumer spend. This fast-paced innovation schedule signals to rivals that surviving on standard flavor offerings alone is no longer viable.
For mid-market operations, this competitive dynamic means they must achieve strict manufacturing efficiencies or risk complete margin compression from rising ingredient costs. The landscape is separating companies that possess integrated, closed-loop extraction and bottling lines from those relying on expensive third-party ingredient processing. Over the next 12 to 24 months, expect this separation to trigger consolidation, as dominant conglomerates acquire smaller, specialized functional brands to secure their proprietary ingredient tech.
Recent Developments
Leading market operators expanded the retail availability of antioxidant-infused functional waters throughout the first quarter of 2026 to capture early spring active-lifestyle demand.
Industrial beverage processors integrated high-efficiency, multi-stage fortification lines in late 2025 to lower the production costs associated with vitamin-enriched water variants.
Major brands introduced specialized, zero-sugar tropical fruit lines to align with global regulatory shifts targeting high-fructose corn syrup usage.
Strategic packaging upgrades across dominant North American production lines resulted in lightweight, highly recyclable bottle profiles to meet updated regional circular economy standards.
Regional manufacturing plants across China increased total volume output of mineral-enhanced functional options to secure higher shares in adjacent domestic retail markets.
Strategic Implications
The financial reality of balancing premium natural inputs against competitive shelf pricing requires a thorough review of existing sourcing operations. Formulating with authentic plant extracts and delicate active cultures instead of inexpensive artificial chemicals directly increases raw material expenditure. Procurement executives must establish long-term, fixed-price supply agreements with certified ingredient houses to shield their manufacturing margins from sudden crop or chemical price spikes.
Furthermore, moving into the functional water segment introduces specific formulation stability challenges that standard water processing lines never face. Minerals and active vitamins can alter the clarity, color, and mouthfeel of the liquid base over extended storage periods, risking consumer rejection at the point of consumption. Technical R&D teams must implement advanced stabilization methodologies to ensure the final product looks and tastes exactly as intended throughout its entire distribution lifespan.
Future Outlook
The long-term development of the flavored and functional water market will belong to manufacturers that master the balance between functional ingredient potency and cost-efficient processing scale. Operations that can reliably deliver crystal-clear, clean-label fortified waters without inflating retail prices will secure highly profitable, dominant positions across corporate distribution channels. Conversely, brands that fail to adapt to rising ingredient costs or suffer from formulation instability will see their retail footprints steadily reclaimed by agile, vertically integrated competitors.
Ultimately, future market leadership will reward beverage operations that successfully merge innovative, sugar-free flavor delivery with scientifically verified wellness benefits, while leaving legacy, sugar-heavy carbonated lines to manage shrinking market relevance.
Analyst Perspective
“The flavored and functional water market is no longer a luxury sub-segment; it has transformed into the primary battleground for volume growth across the global beverage industry. Success in this sector requires strict control over raw ingredient supply chains and the technical capacity to deliver advanced physical benefits without compromising product clarity or taste.” — Siddhi Dole, Research Analyst, Maximize Market Research
About Maximize Market Research
Maximize Market Research Pvt. Ltd. (MMR) is a global market research and consulting company that provides reliable, data-focused, and practical business insights. The firm serves a wide range of industries, including healthcare, pharmaceuticals, technology, automotive, electronics, chemicals, personal care, and consumer goods. Through market forecasts, competitive analysis, strategic consulting, and industry impact assessments, MMR helps organizations understand changing market conditions, identify growth opportunities, and make informed business decisions for long-term success.
2nd Floor, Navale IT Park Phase 3
Pune Banglore Highway, Narhe
Pune, Maharashtra 411041, India
+91 9607365656
sales@maximizemarketresearch.com
